Argus Terminal
Local-first simulation of a Bloomberg-style multi-pane trading, L2/L3 orderbook matching, Monte Carlo VaR/CVaR risk, Black-Scholes-Merton SVI volatility surface, FIX 4.4 / binary SBE wire protocol and Nelson-Siegel-Svensson yield curve workstation built on Node.js, built-in node:sqlite and HTML5 Canvas.
What I built
An educational, single-process Node.js simulation of a multi-asset trading and quantitative analysis terminal (using built-in node:sqlite and a single external dependency, ws, with zero frontend bundler):
- 01 — Main Trading Terminal & Dual Matching Engines (
/): Multi-pane workspace with a<GO>command bar, 6 simulated cross-asset instruments (BTC-USD,ETH-USD,SOL-USD,NVDA-EQ,XAU-USD,IDR-USD), price-time FIFOOrderbookwith synchronous SQLite transaction persistence, and a preallocatedTypedArrayarenaSlabOrderbook(capacity = 262,144, intrusive doubly-linked list,O(1)cancel) benchmarked across 250,000 deterministic operations (~2.83M–3.26M ops/secin-memory vs ~25.9k ops/secobject-array baseline). - 02 — Quantitative Risk & Execution Algos: Correlated Cholesky Monte Carlo VaR/CVaR (95% / 99%), Order Book Imbalance (OBI), VPIN-style order-flow toxicity proxy, Stoikov micro-price, OHLCV strategy backtester, and simulated
TWAP,VWAP,ICEBERG, andAvellaneda-Stoikovexecution schedules. - 03 — Derivatives, FIX 4.4 / SBE Wire Codec & Smart Order Router (
/options.html): Analytical Black-Scholes-Merton 1st/2nd-order Greeks with verified Put-Call parity (<1e-8), hybrid Newton-Raphson/bisection IV solver, 5-tenor Gatheral SVI 3D volatility surface, FIX 4.4 parser/builder with Modulo-256Tag 10checksum validation, 40-byte binary SBE frame codec, and 4-venue Smart Order Router. - 04 — Macro Yield Curve, Bond Desk, LOB Replay & Dark Pool (
/macro.html): Nelson-Siegel-Svensson (NSS) yield curve calibration (1M–30Y), fixed-income bond pricing (YTM,DV01, Macaulay/Modified duration, convexity,Z-spread), event-sourced LOB replay time-machine withSHA-256state hash verification, and a simulated midpoint-peg dark pool (ARGUS-DARK-ATS) with minimum acceptable quantity and VPIN toxicity gating.
What was checked
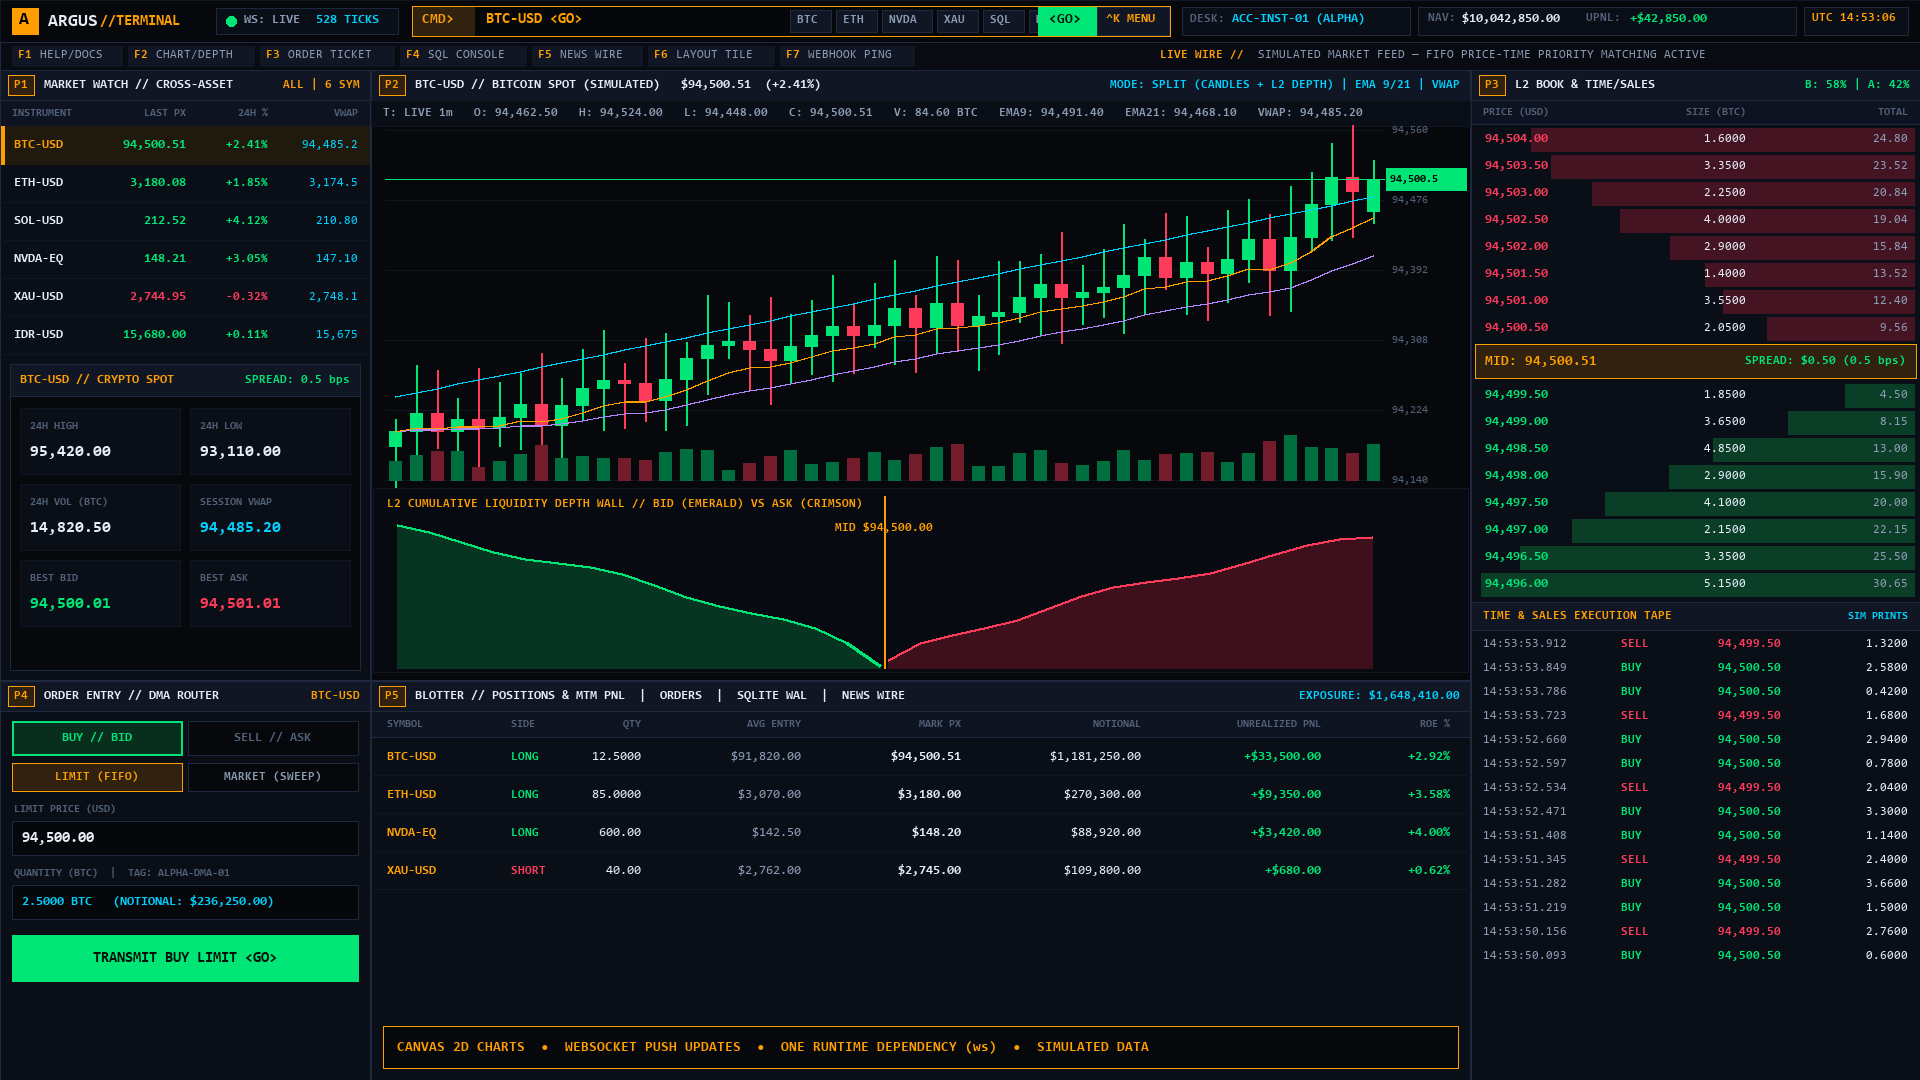
vanovri/argus-terminal showing simulated L2 order book depth, OHLCV candlesticks, trades tape, and blotter panes.Release audit: 25 October 2026. All 6 plain-Node verification suites (64 / 64 assertions across E2E matching, defensive security controls, DevTools layout/a11y invariants, quant risk, BSM/FIX/SBE codecs, and NSS/LOB replay) pass via npm test, alongside a 5-mode 250,000-order ablation benchmark (benchmarks/results/latest.json).
What this demonstrates
Data-structure layout trade-offs in JavaScript (V8 heap object arrays vs. preallocated TypedArray arenas with intrusive linked lists), deterministic financial and numerical modeling (FIFO matching, BSM Greeks, SVI volatility parameterization, Nelson-Siegel-Svensson yield curves, binary wire framing), and defensive API hardening (parameterized SQLite queries, table allowlisting, SSRF private-IP filtering, and RBAC guards). All market data, venues, and accounts are simulated locally.